

How to Build a 5-Year Financial Forecast
By Anran Xie |
Last Updated: October 01, 2026
By Anran Xie |
Last Updated: October 01, 2026
Five-year forecasts get difficult when commitments mature at different speeds. Hiring can hit payroll before a new market reaches revenue, while debt repayments or capital projects follow their own schedules.
This is one reason forecast quality remains high on the finance agenda. In Gartner’s survey of more than 200 chief financial officers (CFOs), 51% ranked improving financial forecast accuracy and quality among their five leading priorities for 2026.
A 5-year financial forecast gives financial planning and analysis (FP&A) teams one view of those timing effects across cash, margins, capacity, and funding.
This guide explains what to include, how a 5-year forecast differs from a 3-year view, how to build and review the model, and which tools keep it current as actuals and assumptions change.
A 5-year financial forecast projects revenue, expenses, profitability, cash flow, and capital requirements across five years. Finance teams use it to test strategic plans, estimate funding needs, prepare board or lender discussions, and understand how operating decisions affect financial capacity beyond the annual budget.
For a more detailed explanation about different forecasting methods and time horizons, see Limelight’s financial forecasting guide.
A 5-year forecast becomes useful when decisions such as market expansion, acquisitions, major hiring, or capital projects create costs or funding needs beyond the annual budget. Common use cases include:
The model should remain a working FP&A document. When actual performance moves away from the original assumptions, finance should update the affected drivers, rerun the analysis, and rebuild the five-year view from the new assumptions.
A 3-year forecast typically supports near- to medium-term execution, while a 5-year forecast extends the view far enough to evaluate longer-term growth, financing, capital allocation, and structural changes. The longer horizon also increases uncertainty, so the model should retain greater detail in the early years and rely on broader, driver-based assumptions as it moves further out.
|
Factor |
3-Year Financial Forecast |
5-Year Financial Forecast |
|
Strategic horizon |
Near- to medium-term execution, hiring, department plans, and growth targets |
Long-term strategy, market expansion, business-model changes, and capital planning |
|
Precision |
More detail from recent actuals, pipeline, known costs, and approved operating plans |
More directional in later years as market, financing, pricing, and capacity assumptions become less certain |
|
Typical use |
Resource planning, hiring approvals, product investment, regional rollouts, and operating-expense management |
Debt financing, fundraising, mergers and acquisitions, IPO readiness, infrastructure investment, and long-term capital allocation |
|
Model detail |
Often monthly or quarterly with cost-center, headcount, pipeline, and operating inputs |
Detailed in early periods, then increasingly driver-based and aggregated in later years |
|
Risk view |
Tracks variance against the operating plan and supports near-term course correction |
Tests liquidity, funding, margin, demand, and execution risks across several scenarios |
|
Communication |
Mainly supports finance, department leaders, and executives |
Often supports boards, lenders, investors, and executive strategy discussions |
The wider horizon increases the risk of false precision. Keep the first 12–24 months detailed enough to support operating decisions, then use broader periods and a smaller number of causal drivers as uncertainty increases.
A 5-year forecast helps finance evaluate the following:
It also gives leadership a basis for sequencing investments, testing downside risks, and identifying assumptions that require closer monitoring.
Deloitte’s Spring 2026 European CFO Survey, which covered 1,136 CFOs across 12 countries, found that 48% were less optimistic about their companies’ financial prospects than three months earlier, up from 25% in autumn 2025.
Although the finding is regional, the speed of the shift is useful for long-range planning. Assumptions that looked reasonable a quarter ago may need to be retested quickly.
A 5-year model translates those shifts into financial consequences. Higher borrowing costs can reduce acquisition capacity. Slower demand can delay hiring or capital expenditure. A funding delay can turn an otherwise attractive growth plan into a cash constraint.
Scenario planning becomes useful when several assumptions could move together. Limelight’s scenario-planning guide explains how finance teams can turn those uncertainties into distinct operating cases.
Sales may want more capacity, product may need development investment, and operations may be planning a new site. A multi-year forecast puts those commitments on one financial timeline.
Leadership can see when investments overlap, which cost centers absorb them, and whether projected cash generation can fund the combined plan. Timing often changes the answer. A project that works comfortably in Year 4 may create a liquidity problem if it moves into Year 2.
A five-year revenue number becomes useful when leadership can see the operating logic underneath it. Boards, investors, and lenders need to know which assumptions drive growth, margin, working capital, cash, and capital requirements.
A well-structured forecast gives finance a defensible narrative around management’s current expectations, the assumptions carrying the most uncertainty, and the financial consequences of stronger or weaker conditions.
Several initiatives can make financial sense individually and still compete for the same capital.
Finance can compare hiring, technology, facilities, equipment, acquisitions, and market launches against projected margins and liquidity. The forecast can then show which initiatives fit the base plan, which require financing, and which need to move later.
Include the drivers capable of materially changing revenue, cost, cash, funding, or timing decisions. Later years need less line-item detail and more disciplined driver logic.
Core components include:
For workforce-heavy businesses, hiring assumptions should connect directly with compensation, capacity, and cash. Limelight’s headcount-planning guide and workforce-planning platform cover the operating and system side of that process.
Cash-intensive models also need enough detail to show when liquidity tightens. Limelight’s cash-flow forecasting guide explains how receipts, payments, working capital, and financing assumptions feed the forward cash view.
Add plausible scenarios for variables capable of changing the decision. A slower hiring plan, delayed funding event, weaker conversion rate, or faster market launch should change both operating assumptions and the related financial outputs.
Start with the decision leadership needs to make, then work backward into the historical data, assumptions, model structure, scenarios, and review cadence required to support it.
Start by defining the decision the forecast needs to answer, such as when external capital is required, whether a market expansion can be funded internally, or how much acquisition capacity the business has.
Finance may need to:
Once the decision is clear, the model can focus on the drivers capable of changing it.
The first part of the forecast should begin with recent actuals. Review enough history to capture seasonality and operating patterns across revenue, gross margin, operating expenses, cash flow, working capital, and cost centers.
Look for recurring patterns in:
Test how those relationships behaved when the business changed. If headcount increased materially, did output rise at a similar rate? If revenue doubled, what happened to customer-success or delivery costs?
Carrying last year’s percentage growth into five more columns misses those operating relationships.
Long-range models often combine several forecasting methods rather than forcing every line through the same logic.
Hidden assumptions are difficult to challenge. Keep major inputs in a controlled assumptions layer and record where each one comes from.
Group assumptions into parallel categories:
For each material input, record the source, volatility, management control, and review cadence.
|
Input |
Source |
Volatility |
Management Control |
Review Note |
|
Headcount growth |
Internal workforce plan |
Medium |
High |
Tie hiring by function to approved capacity plans |
|
Ramp time |
Recent hiring cohorts |
Low to medium |
Medium |
Recheck after role, territory, or onboarding changes |
|
Sales productivity |
Historical and directional data |
Medium to high |
Medium |
Separate base assumptions from stretch targets |
|
Attrition |
Historical workforce data |
High |
Low |
Revisit after compensation, role-design, or labor-market changes |
|
Cost per hire |
Finance and talent data |
Low to medium |
Medium |
Include recruiting, onboarding, and employer costs |
This structure shows which inputs can move the forecast materially, who can influence them, and when a change should trigger a reforecast.
A 5-year forecast model translates assumptions into revenue, expenses, cash flow, profitability, capital requirements, and management metrics.
Keep more operating detail in the early periods. Years three through five should become increasingly aggregated as uncertainty rises. A practical structure is to keep the first 12–24 months monthly or quarterly, then use broader periods later.
Strong model logic can include:
Driver-level data explains why a financial outcome changes. Bookings, win rates, churn, headcount, ramp time, utilization, average contract value, and payment timing are common examples.
Finance teams often evaluate financial forecasting software when spreadsheet formula chains make version control, scenario maintenance, auditability, and collaboration harder than the modeling itself.
Long-range forecasts need alternatives because uncertainty increases with time.
The 2025 FP&A Trends Survey included 459 finance professionals across industries and regions. Only 18% of organizations could run scenarios in real time or within one day, while 33% could do so within a week. Another 19% could not run scenarios at all.
If leadership asks what a six-month hiring delay does to cash and finance needs a week to answer, the model is too slow for the decision.
Build scenarios around material variables with different operating consequences:
A base case should represent management’s current expected path. Alternative cases should model genuinely different operating or financing conditions and the management response each condition would require.
Once the model works mathematically, pressure-test it with the people responsible for executing the plan.
Start with department leaders. Review hiring plans, productivity expectations, cost-center ownership, contract timing, capacity limits, and strategic initiatives. Ask which assumptions remain feasible, which are already under pressure, and what the model may be missing.
Bring the decisions to the executive team:
Review the long-range model at least quarterly and update it sooner after a material variance or strategic decision. High-growth or volatile businesses can refresh near-term periods monthly while keeping later years directional.
Actuals should replace forecast values as periods close. Each refresh should represent management’s current view using the best available evidence.
Choose the tool by model complexity, input ownership, and refresh frequency. A straightforward forecast can stay in a spreadsheet, while multi-entity models with frequent scenarios and department inputs usually need stronger controls.
Excel and Google Sheets are practical and easy when one team owns the model, updates are infrequent, scenario count is low, and inputs come from a manageable number of sources.
Problems emerge when the workbook becomes a coordination system. Version control, broken links, manual imports, hidden assumptions, and duplicated scenarios can consume more time than the forecast itself.
Finance teams often evaluate FP&A software when they need connected actuals, driver-based models, permissions, scenario control, approval workflows, and recurring management reporting.
The 2026 Association for Financial Professionals FP&A Benchmarking Survey found that only 38% of organizations use structured scenario planning, while 43% use rolling forecasts. Organizations using structured scenario planning also completed budgets 11% faster on average.
Technology cannot create planning discipline on its own. It can reduce manual handoffs, keep model logic consistent, and make scenario updates easier to repeat when the underlying process is already defined.
For category-level comparisons, see Limelight’s 2026 financial forecasting software guide.
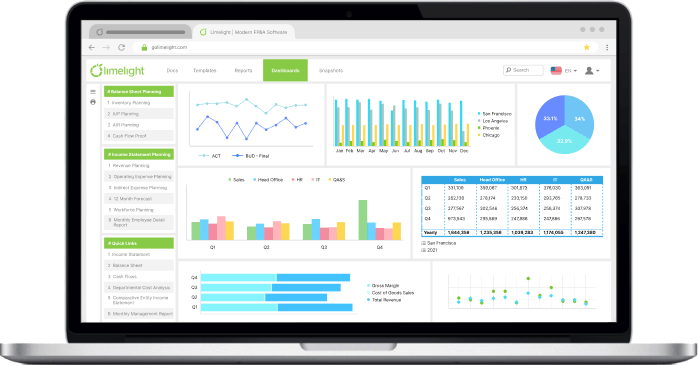
Scenario dashboards give leadership a concise view of revenue, margin, cash, headcount, capital, and other decision outputs.
A governed model should feed the dashboard. Polished visuals cannot fix stale inputs or disconnected calculations. They only make the wrong answer easier to consume.
Templates are useful when finance needs a first model quickly, especially for a board discussion, funding plan, or market-entry case.
Use templates as a starting structure. Replace generic assumptions with the company’s own drivers, cost structure, liquidity constraints, and decision rules before using the output for capital allocation.
Separate files force finance to reconcile actuals, forecast assumptions, workforce plans, scenarios, and board reports after every material change. Limelight uses one finance-owned model for those planning and reporting workflows.
Limelight’s FP&A modeling environment organizes accounts, departments, entities, funds, programs, locations, customers, vendors, employees, and other dimensions in one structure.
The same structure can support actuals, budgets, forecasts, and reports, so finance does not need to rebuild the business hierarchy for each output.
For a 5-year forecast, that gives revenue, workforce, cost, cash, and capital assumptions a consistent model underneath them.
Limelight’s planning environment supports budgets, forecasts, scenarios, driver-based planning, cash-flow forecasting, capital planning, workforce planning, and long-range planning.
Finance can change a driver such as pricing, headcount, volume, or expense growth and carry the effect through the same planning structure rather than maintaining separate scenario files.
Limelight’s reporting tools connect actuals, budgets, forecasts, scenarios, dashboards, drill-down analysis, variance explanations, management reports, and board packages.
Reports can refresh from the latest planning data, which reduces the need to rebuild presentation outputs after each assumption change.
For a broader view of the category, see Limelight’s FP&A software overview.
Book a demo to see how Limelight can support a 5-year planning model in your current finance workflow.
A budget is an approved financial plan for how the company intends to allocate resources, while a forecast is management’s latest estimate of where the business is heading.
The budget can remain fixed for performance measurement. The forecast should change as actuals, assumptions, and approved strategy change.
For decisions involving liquidity, debt, working capital, or external funding, linking the income statement, balance sheet, and cash flow statement gives finance a more complete model.
A narrower forecast can focus on selected outputs, but the cash and financing effects still need to reconcile with the assumptions driving the decision.
Keep inflation and interest rates as explicit external assumptions rather than burying them inside revenue or cost growth.
Use separate scenarios when the plausible range could materially change margins, borrowing costs, capital spending, or funding needs. This makes the effect of each external assumption easier to review and update.
A 5-year forecast can supply revenue, margin, capital expenditure, working-capital, and cash-flow assumptions to a valuation model.
The forecast provides the operating assumptions. A discounted cash flow valuation then adds valuation-specific inputs such as the discount rate and terminal value.
Extend the horizon when the decision lasts longer than the five-year model, including long-lived infrastructure, debt maturities, major contracts, regulated investment plans, or valuation work.
Use less detail as the horizon expands. Later years should depend on a smaller number of transparent drivers rather than increasingly precise line-item assumptions.
Subscribe to our newsletter