Key takeaways
- Zero-based budgeting (ZBB) requires finance and operating leaders to justify funding requests against current needs, service levels, and strategic priorities.
- Decision packages document each activity’s costs, expected outputs, alternatives, and dependencies so leadership can compare requests on consistent terms.
- A funding line separates approved packages from unfunded requests, while mandatory commitments and operational dependencies constrain which combinations are feasible.
- Start with spending areas that justify the review effort, and assess delivered services alongside costs before expanding the process.
Zero-based budgeting is a planning method that requires organizations to justify activities and spending for the upcoming period without automatically carrying forward prior allocations.
Managers document funding requests, and leadership evaluates them against current priorities and available resources.
For financial planning and analysis (FP&A) teams, the challenge is deciding which services and investments deserve funding when requests exceed the available budget. Decision packages, explicit ranking criteria, and a funding line make those choices easier to examine and defend.
In this guide, you’ll learn how zero-based budgeting works, how decision packages and funding limits influence allocation decisions, how ZBB compares with incremental budgeting, and when a targeted or rolling approach makes more sense than a full reset.
What Is Zero-Based Budgeting?
The “zero” in ZBB means previous spending creates no automatic entitlement to future funding. Historical actuals still help managers estimate costs, understand demand, and test whether a request is realistic.
The Government Finance Officers Association’s research on ZBB describes the method as building a budget from the ground up. In the decision-package approach, managers explain an activity’s purpose, cost, service level, and alternatives before leadership decides how much to fund.
Peter Pyhrr helped establish the method in corporate planning and published “Zero-base budgeting” in Harvard Business Review in 1970. Jimmy Carter subsequently used the approach in Georgia and issued a February 1977 memorandum introducing it across the federal executive branch for preparation of the fiscal year 1979 budget.
Organizations can apply ZBB across the business or limit the review to selected departments, programs, or spending categories. The scope should reflect the decisions leadership needs to make and the analytical capacity available.
Zero-Based Budgeting for Businesses vs. Personal Zero-Based Budgets
Corporate ZBB evaluates whether business activities deserve funding. A personal zero-based budget assigns available income to expenses, savings, debt payments, and other goals until no money remains unassigned.
Corporate and personal uses of “zero”
|
Dimension
|
Corporate zero-based budgeting
|
Personal zero-based budgeting
|
|
Main decision
|
Which activities and service levels should receive funding?
|
How should available money be allocated?
|
|
Budget owners
|
Finance leaders, department managers, and program owners
|
An individual or household
|
|
Meaning of zero
|
Prior allocations require fresh justification
|
Available money has a planned purpose
|
|
Main output
|
Approved activities, service levels, and funding amounts
|
Allocations to spending, saving, and repayment categories
|
|
Review cycle
|
Annual, event-driven, or rotating reviews
|
Often monthly, with adjustments as circumstances change
|
A business can approve a budget above or below last year’s spending. Its total follows the activities leadership chooses to fund, subject to financial capacity and operating obligations.
How Does Zero-Based Budgeting Work?
ZBB moves from defining the activities under review to approving funding and monitoring delivery. The decision-package method links each request to a service or outcome, allowing leaders to compare the consequences of funding different levels of activity.
1. Define decision units
Choose the departments, cost centers, programs, or projects that managers can evaluate separately. Assign each decision unit an owner and define its boundaries before collecting requests.
For example, a marketing department might separate website operations from paid campaigns because they have different costs, outputs, and dependencies. Avoid dividing work so finely that preparing packages costs more effort than the decisions warrant.
Agree on strategic priorities, mandatory obligations, and the review timetable at this stage. Managers need those constraints before they can propose credible alternatives.
2. Build decision packages
A decision package describes an activity and the resources needed to deliver it. The Zero-Base Budgeting Manual cataloged by the US Office of Justice Programs emphasizes activities, alternative performance levels, resource requirements, and the consequences of leaving work undone.
Use a consistent template:
- State the activity’s purpose and accountable owner
- Specify the requested funding and assumptions behind it
- Define the expected output and service level
- Compare alternative delivery methods or funding levels
- Identify mandatory commitments and dependencies
- Explain the consequence of reduced or declined funding
Packages can cover operating expenses and proposed capital expenditures, with the relevant timing and approval requirements identified.
Separate the cost of a minimum service level from the additional cost of an enhancement. If two packages represent alternative ways to deliver the same activity, treat them as alternatives when calculating funding requirements. Adding both would overstate the budget.
3. Evaluate and rank packages
Leadership compares packages using agreed criteria such as strategic contribution, service requirements, expected benefits, risk, and cost. Department managers explain operational consequences, while finance challenges assumptions and checks comparability.
Resolve dependencies before finalizing the ranking. A campaign package may depend on website capacity or analytics support, so funding the campaign alone could produce an unworkable plan.
Required legal, contractual, and safety commitments constrain the available choices. Record these requirements explicitly rather than allowing an apparent low ranking to imply that the organization can simply stop meeting them.
4. Allocate funding and set thresholds
The budget envelope is the amount available for the activities under review. The funding line separates approved packages from requests that leadership defers, redesigns, reduces, or declines.
Work through the ranked requests while checking total cost and dependencies. The envelope sets a ceiling. Leadership can leave money unallocated when remaining requests lack sufficient value or cannot be delivered at a viable service level.
Approve the funding amount, service commitment, accountable owner, and conditions for each package. A material change in scope or cost should trigger a defined review rather than an informal increase.
5. Track, review, and reset each cycle
Compare actual spending with approved amounts through budget variance analysis, then check whether each activity delivered its promised output.
Lower spending can reflect efficiency, delayed work, or reduced service. Those outcomes require different responses. Record the cause before classifying an underspend as a saving.
At the next review, reassess the activity’s need, delivery method, and funding level using current evidence. Retain useful historical data while requiring a fresh funding rationale.
Zero-Based Budgeting Example: Ranking Decision Packages Against a Funding Line
Consider an illustrative marketing department with $1.45 million in prior-year spending and a $1.20 million budget envelope for the next year. Leadership evaluates seven requests and ranks them using strategic priorities, required service levels, and expected outputs.
The amounts below represent separate, additive activities. The example assumes the first six packages provide the support needed to deliver the approved marketing plan.
Ranked marketing decision packages
|
Rank
|
Decision package
|
Service level
|
Requested cost
|
Cumulative requested cost
|
Funding decision
|
|
1
|
Marketing operations and planning
|
Minimum
|
$180,000
|
$180,000
|
Funded
|
|
2
|
Brand strategy and governance
|
Minimum
|
$200,000
|
$380,000
|
Funded
|
|
3
|
Website platform and maintenance
|
Current
|
$150,000
|
$530,000
|
Funded
|
|
4
|
Content production program
|
Current
|
$220,000
|
$750,000
|
Funded
|
|
5
|
Demand-generation programs
|
Current
|
$250,000
|
$1,000,000
|
Funded
|
|
6
|
Marketing analytics and reporting
|
Current
|
$200,000
|
$1,200,000
|
Funded
|
|
7
|
Expanded agency support
|
Incremental
|
$180,000
|
$1,380,000
|
Not funded
|
The funding line falls after marketing analytics and reporting. Expanded agency support would raise total spending to $1.38 million, exceeding the envelope by $180,000. Leadership could defer it, reduce its scope, or reconsider another package, provided the revised combination remains operationally feasible.
Approved spending is $250,000 below the prior year’s $1.45 million. That difference is a planned spending reduction. Finance must compare actual costs and delivered services with the approved plan before reporting realized savings.
Zero-Based Budgeting vs. Traditional (Incremental) Budgeting
Incremental budgeting adjusts an existing baseline, while ZBB requires a fresh case for the activities under review. The comparison below covers the starting point, review effort, cost visibility, and allocation risks.
1. Traditional budgeting
An incremental budget begins with prior-period actuals or an existing budget and adjusts for expected changes, such as inflation, staffing, demand, or new initiatives.
This approach reduces preparation work when operations remain stable. Its weakness is the possibility that recurring costs receive less scrutiny than proposed additions. Managers can still challenge those costs, but the method does not inherently require a complete reassessment.
2. Zero-based budgeting
ZBB requires managers to explain the current need for each activity in scope, including established work. Leaders can compare maintaining, reducing, expanding, or replacing a service before approving funding.
The additional review can expose weak assumptions, but its value depends on usable cost data and decision criteria. Producing more documentation alone does not improve an allocation.
3. Comparing the two budgeting approaches
|
Dimension
|
Traditional incremental budgeting
|
Zero-based budgeting
|
|
Starting point
|
Existing budget or prior-period actuals
|
Activities and service levels requiring fresh justification
|
|
Main analytical task
|
Explain changes to the baseline
|
Explain the need, cost, and alternatives for work in scope
|
|
Preparation effort
|
Generally lower when operations are stable
|
Generally higher because managers prepare and evaluate packages
|
|
Cost visibility
|
Depends on how thoroughly the baseline is reviewed
|
Requires explicit information about the activities reviewed
|
|
Main allocation risk
|
Carrying forward outdated spending
|
Favoring easily measured, near-term benefits
|
|
Useful context
|
Predictable operations with a credible baseline
|
Strategic change, cost pressure, or unclear spending rationale
|
A hybrid process can retain incremental planning for stable areas and apply zero-based review where spending needs a deeper challenge.
Advantages of Zero-Based Budgeting
ZBB can improve allocation decisions when managers connect costs to specific activities and leaders act on the findings. The benefits depend on the quality of the review and follow-through.
- It challenges spending retained mainly because it appeared in previous budgets.
- It identifies activities that can be stopped, combined, or delivered at a lower cost.
- It directs funding toward current priorities through explicit comparisons between requests.
- It assigns owners to the costs, assumptions, and outputs behind approved packages.
- It makes the consequences of funding different service levels visible to decision-makers.
- It creates an opportunity to redirect resources when strategy or operating conditions change.
These are potential benefits. A ZBB exercise can also justify maintaining or increasing spending when the business case supports it.
Disadvantages of Zero-Based Budgeting
ZBB requires enough analytical capacity to examine requests and enough governance to act on the results. The GFOA’s research identifies the workload and practical compromises involved in applying the method.
1. Time-intensive
Managers must gather cost data, document alternatives, and explain service implications. Finance then reviews submissions and resolves inconsistencies. A company-wide reset can extend the budgeting calendar and reduce the time available for other analysis.
2. Complexity at scale
Shared services, multiple entities, and cross-departmental dependencies make packages harder to compare. Inconsistent allocations can cause teams to count the same cost twice or overlook costs transferred elsewhere.
3. Departmental resistance
Managers may regard the review as a threat to their teams or established services. If leadership rewards polished justifications over credible evidence, the process can encourage inflated requests and defensive negotiation.
4. Risk of under-investing in long-term initiatives
Research, infrastructure, employee development, and brand investment may take several years to produce measurable benefits. Rankings dominated by immediate savings can weaken those activities.
Evaluate their full costs, risks, and expected benefits over an appropriate horizon. Mandatory commitments and critical operating dependencies also need explicit treatment.
When Should You Use Zero-Based Budgeting?
Use ZBB when leadership needs to reconsider the activities behind a budget and has the capacity to assess alternatives. The strongest starting point is a specific allocation problem.
- Review discretionary spending when financial constraints require choices between competing activities.
- Rebuild funding priorities after a change in strategy, leadership, or operating model.
- Examine cost categories where recurring charges have weak ownership or unclear business justification.
- Compare overlapping functions, vendors, and services during post-merger integration.
Define the decision before choosing the scope. A targeted review of duplicated software or overlapping advisory services may answer the question with less work than a company-wide reset.
When ZBB is a weaker fit
A full reset offers less flexibility when contractual or operational commitments fix most near-term spending. The review may still inform renewal or redesign decisions, but leadership should distinguish immediate choices from longer-term options.
Rapidly changing operations can also make detailed packages stale before approval. Use scenario planning to test uncertain assumptions and keep the review focused on decisions that remain actionable.
If leaders cannot agree on priorities or managers lack reliable cost data, establish those foundations before expanding the exercise.
Real-World Zero-Based Budgeting Examples
Documented examples show how organizations have applied ZBB, but an implementation plan and a reported financial outcome provide different evidence. Check what each source actually establishes before using it as a benchmark.
1. Government example: City of Houston
Houston’s FY2021 ZBB implementation plan, dated October 31, 2019, proposed applying the approach to its General Fund. It outlined establishing city priorities, identifying core services and cost drivers, building decision packages, and allocating available resources.
The document demonstrates a proposed process and scope. It does not establish the savings ultimately achieved or confirm that every planned step occurred.
2. Corporate example: Hindustan Unilever
Hindustan Unilever’s 2017–18 annual report describes ZBB as part of its approach to overhead discipline and cost reduction. It also describes an enterprise-wide savings program involving several functions.
This historical example establishes corporate use of ZBB. It does not isolate a savings amount attributable solely to the budgeting method.
3. Corporate application considerations
A useful example identifies the activity reviewed, the service requirement, the alternatives considered, and the decision made. A company-wide margin improvement alone cannot show whether ZBB caused the result.
For an internal pilot, retain the original request, approved package, implementation cost, and subsequent operating results. Those records let finance assess whether the review improved the decision.
How Finance Teams Use Zero-Based Budgeting in 2026
For a 2026 spending review, finance teams can apply zero-based analysis to selected costs where usage, ownership, or expected output is unclear. Assess each category against its business purpose, service requirements, and available alternatives.
- Review software and artificial intelligence (AI) subscriptions against active users, overlapping functionality, usage, and renewal commitments.
- Reassess professional fees against a defined scope, deliverables, internal alternatives, and the consequence of stopping the engagement.
- Compare marketing programs using their intended outcomes, measurement limits, and the support required to execute them.
- Examine post-acquisition general and administrative costs for overlapping vendors, roles, facilities, and processes.
Each review should produce an explicit decision to retain, reduce, replace, expand, or stop an activity. Track implementation costs and service effects alongside any spending reduction.
Zero-Based Budgeting Best Practices
Set the scope, evidence requirements, and decision authority before asking managers to prepare packages. These controls reduce avoidable work and make the approved budget easier to execute.
1. Consider rolling ZBB to manage workload
Use a rotating review schedule when a full annual reset would exceed available capacity. Finance might review selected cost centers this cycle and others in subsequent cycles, with earlier reassessment when risks change.
Define this schedule explicitly. Rotating ZBB reviews determine which activities receive fresh scrutiny, while rolling forecasts update financial expectations over a continuing time horizon.
2. Standardize the decision-package template
Use the same fields for cost, output, service level, alternatives, assumptions, and consequences of reduced funding. Require managers to distinguish stand-alone costs from incremental enhancements and identify dependencies.
A common template improves comparability without requiring every activity to use the same performance measure.
3. Secure executive sponsorship
Name the leaders who set criteria, resolve disputes, approve exceptions, and authorize funding changes. Explain how decisions will affect departmental budgets before submissions begin.
Managers need confidence that leadership will apply the rules consistently, including to established executive priorities.
4. Evaluate long-term investments over appropriate horizons
Identify mandatory commitments and agree on how to evaluate multi-year investments. Protect required service levels while assessing discretionary investment against appropriate benefit horizons and review milestones.
A long-term label should not automatically preserve a project’s full allocation. Its business case still needs evidence, ownership, and a mechanism for reassessment.
5. Use driver-level data
Build costs from the activities that create them. Driver-based planning can connect requests to headcount, transaction volume, service demand, usage, or unit cost.
For example, a software package should identify required users and license rates. A professional-services package should connect estimated hours or deliverables to the requested fee.
6. Review implemented savings each cycle
Assign an owner and implementation date to approved changes. Track actual spending, transition costs, and the service delivered after the change.
Separate recurring savings from delayed spending and one-time reductions. Check whether costs reappear in another department or account before treating the change as a lasting improvement.
How FP&A Software Supports Zero-Based Budgeting
FP&A software can connect the financial inputs and monitoring needed for ZBB, including cost assumptions, funding scenarios, actuals, and review commentary. Finance still owns the ranking criteria and approval decisions.
Spreadsheets can limit ZBB execution
A controlled spreadsheet can support a small pilot. Problems arise when many owners submit different template versions, use different actuals snapshots, or change assumptions without a clear record.
As the review expands, finance needs consistent data, access controls, and a way to preserve the relationship between approved funding and subsequent results.
How Limelight supports the ZBB process
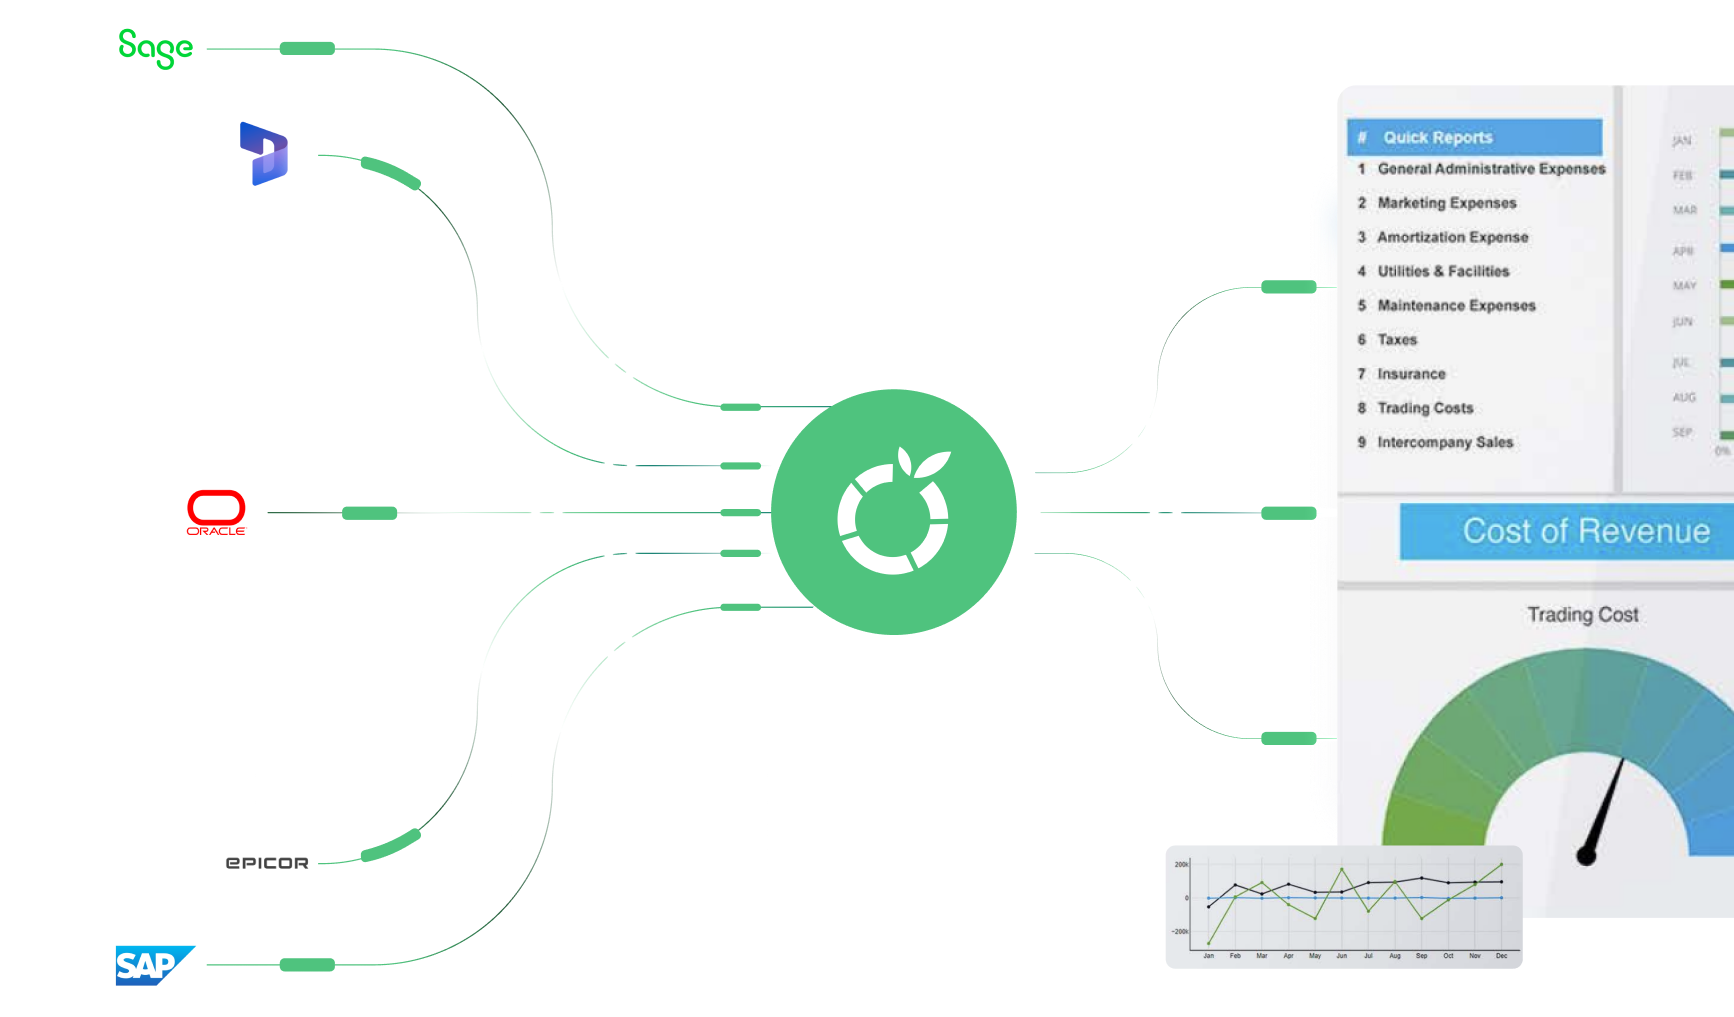
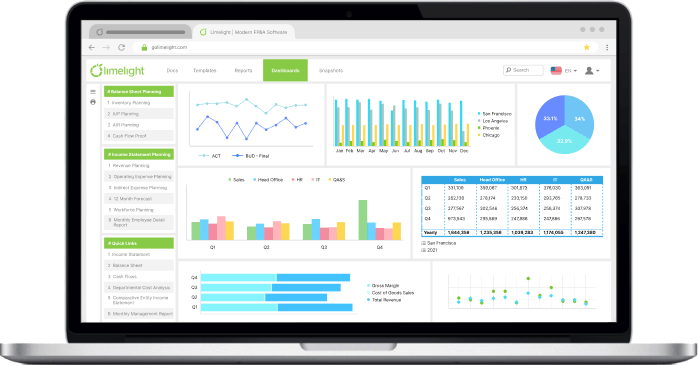
Limelight’s financial modeling capabilities organize accounts, departments, entities, and other dimensions in a shared structure. Finance can use that structure to analyze actuals, budgets, and forecasts consistently.
Its planning and forecasting tools support driver-based assumptions, scenarios, refreshed actuals from enterprise resource planning (ERP) systems, comments, and change tracking. These capabilities help teams compare funding alternatives and maintain context around planning inputs.
Its reporting tools compare actuals with budgets and forecasts, with comments, explanations, and supporting attachments alongside the numbers. Finance can use those reports to investigate spending differences after approving the budget.
To assess how these capabilities would support your own review process, book a Limelight demo.
FAQs
What is the difference between zero-based budgeting and traditional budgeting?
Zero-based budgeting requires a fresh justification for activities and spending within the review’s scope. Traditional incremental budgeting starts with an existing budget or prior-period actuals and adjusts for expected changes. ZBB generally requires more analytical work because managers must explain existing activities as well as proposed additions.
What is a decision package in zero-based budgeting?
A decision package is a documented request to fund an activity at a specified service level. It explains the cost, purpose, expected output, alternatives, dependencies, and consequences of reduced or declined funding. Leaders use packages to compare requests and decide which combination of activities the organization can support.
What is an example of zero-based budgeting?
An illustrative marketing department receives a $1.20 million spending limit and submits seven ranked packages totaling $1.38 million. Leadership approves six packages costing $1.20 million and defers a $180,000 agency-support request. The decision follows the current case for each activity, while prior-year spending supplies context for evaluating the new plan.
How often should a company use zero-based budgeting?
Set the cadence according to the decisions needed, cost volatility, and available review capacity. A company can run an annual review, reassess selected categories after a major change, or rotate cost centers across planning cycles. Revisit a package sooner when demand, contractual commitments, or service requirements materially change.
Is zero-based budgeting only used for cost-cutting?
No. ZBB can be used to redirect funding toward current strategic priorities, compare different service levels, evaluate alternatives, and decide whether activities should be retained, reduced, replaced, expanded, or stopped. A ZBB review can justify maintaining or increasing spending when the business case supports it.
What are the main disadvantages of zero-based budgeting?
The main disadvantages are the time and analytical effort required to prepare and evaluate decision packages, the complexity of comparing activities with shared costs or dependencies, and the risk of departmental resistance. ZBB can also underweight long-term investments if rankings focus too heavily on immediate savings rather than the appropriate benefit horizon.
Who invented zero-based budgeting?
Peter Pyhrr helped establish zero-based budgeting in corporate planning and published “Zero-base budgeting” in Harvard Business Review in 1970. Jimmy Carter later used the approach in Georgia and introduced it across the federal executive branch in 1977 for preparation of the fiscal year 1979 budget.
Is a business zero-based budget the same as a personal zero-based budget?
No. Corporate ZBB evaluates whether business activities and service levels deserve funding. A personal zero-based budget assigns available income to expenses, savings, debt payments, and other goals until no money remains unassigned. The “zero” therefore has a different meaning in each context.
Can zero-based budgeting work with rolling forecasts?
Yes. ZBB determines which activities deserve funding, while a rolling forecast updates expected financial results and extends the forecast horizon as periods close. Finance should preserve the approved budget as a reference so it can distinguish changes in the outlook from authorized changes in spending or scope.
Does zero-based budgeting work for nonprofits?
ZBB can work for nonprofits when leadership needs to reassess activities, service levels, and funding priorities. The same decision-package principles can be applied, with particular attention to restricted funding, mandatory commitments, program dependencies, and the consequences of changing service levels. The scope should match the decisions leadership needs to make and the organization's analytical capacity.